Will Aging Baby Boomers Make Housing More Affordable?

Millions of homes will change hands. Whether they become homes the next generation can afford is a different question.

Begin the story
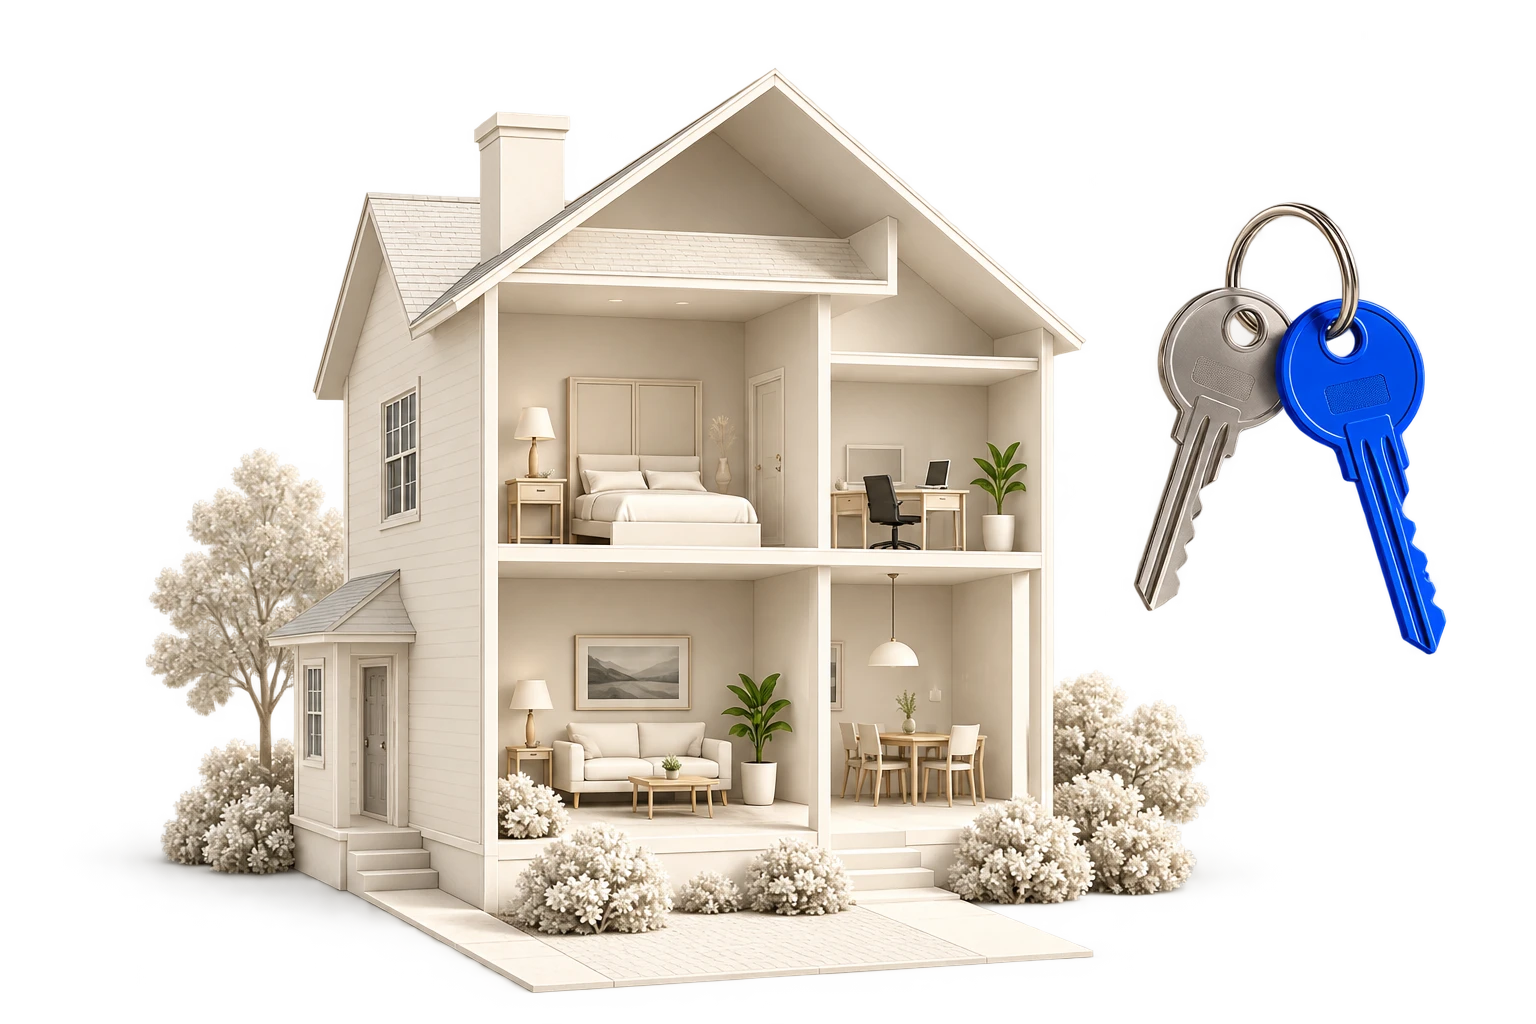
Conceptual ivory cutaway home and two keys, one silver and one blue: the same home can pass through different arrangements.
Conceptual architectural illustration, not a reported home.

Begin with a house, not a wave.

In this thought experiment, a daughter inherits the home in which her father lived. She moves into it. The name on the deed changes. Her address changes. The house has acquired a new owner without acquiring a for-sale sign.

Something important has happened. She has a place to live, perhaps on terms she could never have obtained through an ordinary purchase. But the family searching the listing sites down the street has not been offered that house. A transfer has occurred. A listing has not.

Now change one decision. The daughter sells instead. This time the home can enter the market, although its price, condition and location will determine who can buy it. Change the decision again: she rents it out. A tenant can gain a home without a first-time buyer gaining a purchase opportunity. Each version begins with the same walls. Each ends in a different housing market.

This is the difficulty hidden inside one of real estate's most seductive promises: that the aging of the baby boom generation will release enough homes to make housing affordable again. It offers a comforting timetable to people who have run out of comfortable budgets. The houses exist. Their owners are getting older. Surely the arithmetic must eventually favor those waiting outside.

There is a real demographic change behind that hope. Realtor.com's October 1 reporting drew attention to new Harvard research on aging and housing demand. The underlying September 24 analysis by Daniel McCue found that households headed by baby boomers declined by 3.5 million between 2015 and 2025. The oldest members of the generation, born in 1946, turn 80 this year.

But a change in the number of boomer-headed households is not a count of homes listed for sale. Nor is it a count of homes a young family can afford. Between those statements lie decisions, other households, repairs and places that cannot be picked up and moved.

The answer to the title's question is therefore a qualified yes: turnover can help. It will not help everywhere, on the same schedule, or through the same route. We need to follow the house farther than the headline does.
What disappeared from the count?

There is a small administrative detail with unusually large consequences here. A household is not a generation, a family tree or a deed. For Census housing statistics, it is the person or people occupying a housing unit. One member is designated the householder. The Census's definitions distinguish that reference person from the physical dwelling.

Imagine a home occupied by an older parent and an adult child. If the parent dies and the child becomes the householder, the home need not become empty. It can disappear from the count of older-headed households while remaining an occupied house. This is an illustrative counting example, not an estimate of how often that happens.

That distinction does not invalidate demographic research. It tells us what the research measures.

A population cohort can become smaller while the surviving people remain independent for longer. McCue finds precisely that combination: fewer boomer-headed households over the decade, alongside a higher household-to-person ratio within the generation. A shrinking cohort and persistent demand for separate homes can coexist. The net count alone does not describe a stream of empty rooms.

A market argument therefore needs several translations. People become households. Households occupy dwellings. Changes in occupation may produce transfers, listings or rentals. Only then can we ask what becomes available to a particular buyer.

Skipping a translation makes the result look more certain than it is. It also makes a person disappear twice: first from a statistical category, then from the explanation of what actually happened to their home.

One home.
Six possible handovers.

Schematic choices, not national transition shares.

An intact ivory architectural model of the same home.THE SAME HOME

A familiar house.
Different possible next chapters.

New owner. No for-sale sign.

Ownership transfers
The same physical home
Heir moves in
Route to market
No sale listing in this case
Onward demand
Previous living arrangement unknown

An heir's old rental might become available, or the move might create a separate household. This schematic does not assume either.

One existing dwelling throughout. These routes do not add physical housing stock without construction or conversion. No probabilities or price effects are assigned.

Consider the routes without assigning them invented national percentages.

An older owner remains at home. No transfer is required. A smaller household can continue to occupy the same number of bedrooms. The unused room may look like spare capacity to a housing analyst; to its occupant it may be the room in which family can stay.

An heir occupies the property. Ownership changes off market. If the heir leaves a rental, another dwelling may become available farther along the chain. If the heir previously lived with relatives, the move may create a separate household. We cannot count the onward effect without knowing the previous living arrangement.

An heir sells. There may be an open-market opportunity. The sale reallocates an existing home; it does not build an additional one. Whether it eases a local shortage depends on the demand waiting for that type of home.

An heir becomes a landlord. The property can serve another household through renting. That is housing access, even if it does not satisfy a would-be owner's goal. Calling it no relief would confuse ownership with shelter. Calling it a new sale listing would confuse two markets.

An owner downsizes. A larger home can be released, while the owner seeks a smaller one. That can improve the fit between households and rooms. It can also increase competition for the smaller, accessible properties already sought by other buyers. One sale and one purchase need not cancel in the same neighborhood or price bracket.

Finally, a house is held while the family settles its arrangements or prepares it for occupation. It may be physically empty without being offered to anyone. The Census has long distinguished vacant homes for sale or rent from other vacancies, including homes held for settlement of an estate.

These are mechanisms, not measured shares. Their importance is the question they force us to ask of every large number: available through which route, to whom, and when?

OBSERVED TRANSFERS / NOT LATER LISTINGS

A family handover.
A different route into ownership.

340,000US homes transferred through inheritance
7%of observed property transfers
Cotality, January 19, 2026; twelve months ending August 2025. Not boomer-only. Subsequent sale, rental or occupation is not measured by these two figures.

Inheritance can solve a family's problem without solving the market's

Cotality's January 19, 2026 analysis of property deeds reports 340,000 US homes transferred through inheritance in the twelve months ending August 2025, representing 7% of observed property transfers. In California, it reports nearly 60,000 inherited properties and a share of about 18%.

Those are transfers, not subsequent listings. The national figures do not identify the age of every former owner, how many heirs moved in, or how many homes were later sold. We should not convert them into a national off-market retention rate.

Still, they make the distinction tangible. A family's route into ownership can run through a relative rather than a mortgage approval and a bidding process. That can provide enormous security to the beneficiary. It cannot provide the same direct opportunity to someone outside the family.

California adds a specific institutional reason to examine the route. Under Proposition 19, qualifying family-home transfers can preserve favorable property-tax treatment when the transferee uses the home as a principal residence, subject to eligibility, value limits and filing rules. The applicable additional exclusion amount for transfers from February 16, 2025 through February 15, 2027 is $1,044,586 above the factored base-year value. It is not a blanket exemption on every inherited property's first million dollars, and the benefit is not automatic. The Board of Equalization directs people to obtain advice on their own circumstances.

The broader lesson does not require every state to have California's rules. Housing institutions help determine whether a home is kept, occupied, rented or sold. Demography supplies a changing set of circumstances. Families respond within laws, budgets and obligations.

An inheritance also need not arrive at the moment a first-time buyer needs it. Waiting for a family asset is not a housing policy, and the family asset is not guaranteed to survive unchanged until the handover. Care, debts, repairs and several people's needs may have to be paid from the same property.

We can welcome the security inheritance provides without mistaking it for an open invitation to the street.

SELECTED METROS / THE EVIDENCE

The homes are not
where the need is equal.

Potential homes are not current listings. Even before the handover, the local comparisons differ.

Potential homes.
Young renter families.

Data CSV
Selected boomer homes Young renter families
Los Angeles
Selected homes: 146 thousand
Young renter families: 430 thousand
New York
Selected homes: 263 thousand
Young renter families: 611 thousand
Washington
Selected homes: 150 thousand
Young renter families: 155 thousand
Atlanta
Selected homes: 161 thousand
Young renter families: 163 thousand
Counts in thousands, common zero baseline. Selected approximate published counts. ACS 2020–2024, Indiana University analysis, Spring 2026. Potential stock, not listings; renter families are a proxy, not active buyers. A local price percentile is not an income-based affordability test.
Definitions and underlying counts

Homes: boomer owner households, 1–2 people, at least 2 excess bedrooms, value below the local 75th percentile. Families: renter households headed by someone aged 25–45, with children under 18.

Selected approximate ACS counts
MetroHomesFamilies
Los Angeles146,000430,000
New York263,000611,000
Washington150,000155,000
Atlanta161,000163,000

A house cannot follow a job opening across the country.

That immobility is the weakness in a national promise. The useful comparison is not simply older homeowners against younger people. It is potentially suitable homes against households seeking housing in the same local market.

In a Spring 2026 Indiana University analysis, finance professor Isaac Hacamo uses 2020–2024 ACS data to examine fifty large metropolitan areas. His potential-supply category is specific: boomer-occupied, one- or two-person owner households, at least two excess bedrooms, and a value below the local 75th percentile. His demand proxy is renting households headed by someone aged 25–45 with children under 18.

The selected counts tell different stories. Los Angeles has roughly 146,000 potential homes against 430,000 young renter families; New York has 263,000 against 611,000. Washington's 150,000 against 155,000 and Atlanta's 161,000 against 163,000 are much closer.

These are potential stocks, not upcoming listings or a promise that each family qualifies to buy. Below a local price percentile is not an income-based affordability test. The comparison excludes younger households without children. It cannot be treated as a complete shortage estimate.

Its value is the contrast. Near parity in a selected proxy does not complete the handover. A large mismatch makes the idea of demographic turnover as a complete solution still harder to defend.

The ratio is a starting question for a city, not a closing answer for a buyer. Where are the homes? What do they cost after repairs? Can residents reach work, school and care from them? Who else will bid?

The same generational change can create useful openings in one place while leaving another place with far too few suitable homes. A national average will make those experiences look like neighbors. They are not.

ILLUSTRATIVE / TWO CLOCKS

A cheaper house.
A harder first cheque.

A lower price can reduce the payment while repairs increase the cash needed to start. Change two assumptions. Keep the loan terms the same.

Reference home: $450,000.
Comparison: $382,500.

Upfront cash

Down payment, closing costs and cash repairs

Reference home$103,500
Repair home$132,975
Purchase cash Cash repairs

Monthly principal & interest

Purchase mortgage only, no repair financing

Reference home$2,395
Repair home$2,036
Taxes and insurance are not included.
$29,475more cash upfront for the cheaper home
0% to 30%
$0 to $100,000

Repairs above $15,525 erase the initial purchase-cash saving at this discount.

Illustrative: $450,000 reference, 20% down, 3% closing costs, common 7% fixed rate for 30 years. Comparison repairs paid upfront in cash. Excludes taxes, insurance, mortgage insurance, utilities, reserves, work delays, credits and future upkeep. Not a lender offer or repair estimate.

Even a well-located home can require a second transaction before it is ready: the transaction with the roof, the wiring, the heating system and the years.

Harvard's Improving America's Housing 2025 reports a median housing-stock age of 44 years in 2023. Average homeowner maintenance spending on homes built before 1980 was 76% higher than on homes built since 2010. Those are national observations about age and spending, not a diagnosis of any particular inherited house. An older home can be beautifully maintained; a newer one can have expensive defects.

For a cash-constrained buyer, however, the timing of necessary work matters as much as its total cost.

Take a deliberately illustrative comparison. A move-in-ready home costs $450,000. The buyer puts down 20%, pays assumed closing costs of 3% and borrows the remaining purchase price at a fixed 7% for thirty years. Upfront purchase cash is $103,500. Monthly principal and interest are about $2,395.

Another home is 15% cheaper: $382,500. With the same assumptions, its monthly principal and interest fall to about $2,036. But suppose it needs $45,000 of repairs paid in cash at the outset. Purchase cash plus those repairs becomes $132,975, or $29,475 more than for the first home.

The cheaper house has the lower mortgage payment and the higher immediate cash requirement. Neither number contradicts the other.

This calculation assumes repairs are not financed, no seller credit and no difference in taxes, insurance, mortgage insurance, utilities or future upkeep. Actual renovation finance can change the timing and the payment. It does not make the work free. Nor does every repair dollar translate into an equal increase in resale value.

Under this example's down-payment and closing-cost assumptions, the 15% price discount saves $15,525 of upfront purchase cash. Repairs above that amount erase the initial cash saving. That threshold is the useful insight, not a prediction that inherited homes need $45,000 of work.

Move the discount and repair assumptions in the study. Watch the purchase price become easier while the first cheque can become harder.

Restoring existing homes may be one of the most important ways demographic turnover becomes useful housing. But the restoration has to be funded by somebody, at some point before a household can safely enjoy the result.

THE TIMETABLE / A FEBRUARY 2024 PROJECTION

The timetable was never
a single breaking wave.

A birth cohort spans years. Its housing choices do too. The published model describes a gradual sequence, not a count of houses suddenly coming up for sale.

Projected decline, millions
relative to 2022
Data CSV
05100.320232.720289.2203505100.320232.720289.22035
Every point: Freddie Mac projection published February 2024. Boomer homeowner households, not observed listings. Connecting segments show the published annual sequence, not continuous observed change.
Inspect the annual projections
February 2024 projections, relative to 2022
YearMillions fewer homeowner households
20230.3
20240.6
20251.0
20261.5
20272.1
20282.7
20293.4
20304.2
20315.1
20326.0
20337.0
20348.0
20359.2

The word tsunami promises an arrival. Birth cohorts supply a span.

The baby boom covers nineteen birth years, from 1946 through 1964. In 2026 its members are roughly 62–80. Treating everyone in that range as about to leave home replaces different lives with one calendar event.

Freddie Mac's February 2024 outlook illustrates the slower shape. Its historical-retention model projected 2.7 million fewer boomer homeowner households by 2028 and 9.2 million fewer by 2035, relative to 2022. It also noted that using more recent, higher retention rates would reduce the projected decline by about one million.

These are dated model outputs, not counts of actual 2026 listings. They concern homeowner households, whereas the new Harvard observation concerns all boomer-headed households. The periods differ too. We cannot subtract one series from the other to measure homes withheld from sale or to declare either model vindicated.

The comparison is useful for another reason: it shows how the assumption about remaining independent changes the schedule. A generation can have a large eventual effect without supplying a conveniently timed flood of houses.

Waiting is not costless for those hoping to buy. A decade in a demographic chart can include several rent renewals, a change of job, the arrival of a child and years of saving. For an older owner, the same decade can mean years of living well in a familiar place. The buyer's impatience and the owner's attachment are not mathematical errors. They are the lives the chart must serve.

A sensible forecast should not resolve that tension by pretending everyone moves at once.

Fewer new households is not no need for new homes

The other side of the handover is the household that arrives.

Harvard's published scenarios for 2025–2035 show projected household growth of 6.9 million under low immigration, 8.6 million in the main series and 11.2 million under high immigration. The losses of the cohort aged 55 and over in 2025 change much less across those scenarios than the additions from the younger cohort. These are conditional projections, not a forecast of today's policy or next year's selling prices. Cohort age is fixed at 2025; the people subsequently grow older. Published rounded components need not sum exactly to the reported totals.

Future demand is not written entirely on existing owners' birth certificates. New arrivals, independent households and the decisions that make separate living possible also matter.

There is another consequential qualification in the January 2025 research paper. Its main-series estimate of 11.3 million additional homes needed in 2025–2035 covers household growth, second homes and replacement of units lost from the stock. It does not add the homes needed to eliminate an existing shortage. The methodology also does not model economic cycles or supply constraints as a market forecast would.

Slower growth of a problem is not its repair.

And a home released in one place cannot satisfy unmet demand in another simply by appearing in the same national total. Keeping a usable dwelling in service matters. Building where additional households need to live matters too. Those are complementary tasks, not competing slogans.

The constructive question is where turnover can do more of the work, and where it cannot. Answering it requires evidence about location, condition and demand, not just an estimate of how many owners will be older.

Older households decline.
Other households arrive.

Conditional household changes, 2025–2035. Cohort age in 2025, not at the end of the projection.

Low immigration

Under 55 in 2025+22.6m
55+ in 2025-15.8m
Reported net change+6.9m

Main series

Under 55 in 2025+24.2m
55+ in 2025-15.6m
Reported net change+8.6m

High immigration

Under 55 in 2025+26.6m
55+ in 2025-15.4m
Reported net change+11.2m

JCHS conditional projections, September 24, 2026. The 55+ cohort includes generations other than boomers. Rounded components may not sum to reported totals. No national price effect is modeled.

The smaller home
that has to exist first.

A one-level home. A route to care. A familiar neighborhood. The move needs a possible destination.

Follow the older occupant
Conceptual sunlit one-level living room with a wide, level doorway to a neighborhood.
Conceptual illustration, not a reported home or an accessibility certification.

We have followed the older house toward a younger occupant. Now follow the older occupant toward a possible next home.

Downsizing sounds like subtraction: fewer bedrooms, less upkeep, a smaller bill. But it can require something absent from the neighborhood. A one-level home. A lift. A manageable rent. A route to the doctor. A place close enough that family can still come by.

AARP's 2024 national survey, released December 10 that year, found that 75% of adults aged fifty and over wanted to remain in their current homes for as long as possible; 73% wanted to remain in their communities. These are stated preferences, not predictions of future moves. The survey also found 44% expected to relocate. Wanting continuity and expecting change can coexist.

Do not turn that attachment into an accusation of inefficient occupancy. The number of bedrooms does not measure the value of a neighbor, a familiar route or a family visit. Nor does ownership guarantee abundant resources. Harvard's 2023 older-adult housing report found that 41% of homeowners aged 65–79 carried a mortgage on their primary home in 2022, including home-equity borrowing, compared with 24% in 1989.

A house can be an asset while the person inside it faces a tight budget. It can contain spare bedrooms without containing an affordable alternative address.

That points toward a less adversarial housing strategy. More small, accessible homes near existing communities could make voluntary moves feasible. Adaptation can make staying safer. Rehabilitation can prepare homes for later occupants. Rental options can provide mobility without requiring another purchase. Additional construction can serve households whose needs will not be met by the existing stock.

These are ways to improve the handover, not evidence that every older owner should hand over a house. Their success should be measured in choices people can actually exercise.

What to watch instead of the wave

If you are a buyer, do not ask only whether older residents are numerous. Ask whether suitable homes are being offered, what work they need, what the whole move costs and whether the timing fits your life. An estate sale is not automatically a discount. A discount is not automatically affordable cash flow. A lower mortgage is not automatically enough cash to begin.

If you are studying a local market, separate stock from flow. Count the potentially relevant homes, then observe how many enter the sale or rental market over a defined period. Track reoccupation, rehabilitation and time between an exit and the next use where reliable data allow. State what your data cannot see. A deed file, a vacancy survey and an MLS feed answer different questions.

If you are planning housing, place the incoming household and the departing household on the same page. A shortage of accessible alternatives can frustrate a move; a shortage of repair finance can frustrate the next occupation. Filling either gap can help an existing home serve people better. Where geography or the numbers do not line up, the case for additional homes remains.

There is a hopeful story here, just not an automatic one. A home built decades ago can shelter another generation. Rooms can be used differently. A property can pass through a family or across a market. Work can return a neglected building to useful life. None requires the house itself to be new.

Return to the daughter at the beginning. Whether she occupies, rents or sells the house, the important event is not simply that a document changes. It is that the building continues to provide a place to live, under an arrangement someone can sustain.

The house is already there. The next home is not guaranteed.

Making the two become the same place is the work ahead.

Notes on the evidence
and interactive studies

Research checked October 5, 2026. The news hook is October 1 coverage of research released September 24. Other sources are explicitly dated context, not releases from the past day. No named household or dialogue in this article is presented as reporting.

The handover explorer is a schematic of distinct possible arrangements for one existing dwelling. It has no probability weights, national transition estimates, price forecast or assumption that an heir's previous home becomes vacant. Downsizing is shown as a potential sale plus replacement demand in a potentially different submarket. None of these routes increases physical stock without construction or conversion.

The metro figure uses selected approximate published counts, not a reconstruction of unpublished microdata. Ratios do not measure listings per active buyer. Downloaded rows preserve their definitions and source.

Every point in the timetable is a February 2024 projection, including years that have since passed. The figure supplies no observed series with which to validate it.

The scenario study displays published totals rather than recomputing them from rounded components. It does not estimate a national price change.

The cash study is a reproducible hypothetical, not a repair estimate, lender offer or recommendation. Reference price P = $450,000; comparison price Q = P × (1 − discount). Down payment = 0.20 × price; assumed closing costs = 0.03 × price; repairs are paid upfront in cash only for the comparison. Reference cash = 0.23P; comparison cash = 0.23Q + repairs. The common purchase mortgage is 0.80 × price. Fixed monthly rate r = 0.07/12; M = principal × r / (1 − (1 + r)^−360). The repair amount that eliminates the upfront saving is 0.23(P − Q). Taxes, insurance, mortgage insurance, utilities, reserves, work delays, credits and future upkeep are excluded. Financing repairs changes both cash timing and debt; it is not modeled here.

The interactive studies are educational illustrations, not individual financial or legal advice. Their assumptions are not national estimates of repairs, inheritance behavior or future prices.

Read the article as Markdown

The house is already there.
The next home is not guaranteed.

More insights